Our homeowners renewal notice came the same week as back-to-school night at the middle school, and I opened it at the kitchen table expecting the worst. The premium for the year starting November 1 is $1,511. Last year it was $1,436. That's $75 more, an increase of about 5.2 percent.
A year ago, an envelope like this sent me straight to the phone. In the fall of 2025 our old insurer, Allstate, offered a renewal at $1,927, up 14 percent from the $1,684 we'd paid the year before. We gathered quotes through an independent agent in town plus one direct, and switched to NYCM with a $2,500 deductible at $1,436 a year. I wrote all of that up last October. This renewal is the first real test of whether the switch was a one-year bargain or a decent fit.
Two years, side by side
- 2024 to 2025, Allstate: $1,684, $1,000 deductible
- Allstate's renewal offer for 2025: $1,927
- 2025 to 2026, NYCM: $1,436, $2,500 deductible
- 2026 to 2027, NYCM: $1,511, same deductible
Even with the increase, we're paying $173 less than two years ago and $416 less than Allstate wanted last fall. A 5 percent bump in a year when everything from lumber to tomatoes costs more doesn't alarm me. My own rule, and it's only my rule, is to shop again when a renewal jumps 10 percent or more, or when something big about the house changes.
The porch question
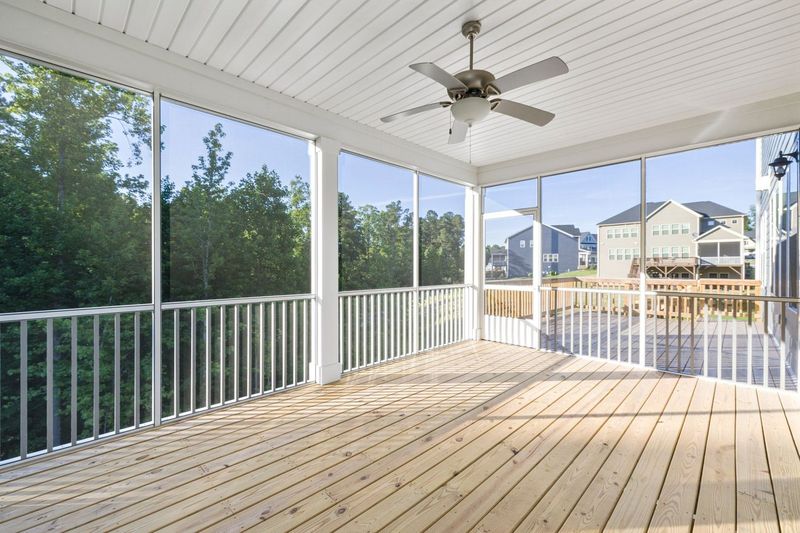
Something about the house did change this year. In early June our carpenter, Kevin, replaced 64 square feet of rotted porch floor, rebuilt the base of the southwest column, sistered a rotted joist and put new flashing at the corner, for $6,640. We paid for it out of savings. It was never a claim.
When I called our agent to go over the renewal, I mentioned the porch, and she asked for a copy of Kevin's invoice and a few before-and-after photos for our file. What she told us about our policy was this: rot and gradual wear are generally treated as maintenance, not as something homeowners insurance pays for, and having a documented repair on record is useful if questions ever come up about that part of the house later. The repair didn't change this year's premium. I emailed her the invoice that night, along with a photo of the new column base, primed and freshly painted.
I also asked whether our $438,000 dwelling coverage, the figure we raised it to last year on her replacement-cost estimate, still made sense. She walked me through how that estimate is built and said she'd flag it if anything looked low. I'm not qualified to second-guess that number, so I wrote down what she said and put it in the folder.
Why we're keeping the $2,500 deductible
Last year NYCM quoted $1,598 with a $1,000 deductible and $1,436 with $2,500, a difference of $162 a year. Over two years, that's about $324 we've kept. In exchange, we've agreed to cover the first $2,500 of any claim ourselves.
For us, the reasons haven't changed. When the maple limb came down in July 2025, the damage came to $1,960, and we paid it ourselves even with a $1,000 deductible, because our Allstate agent explained that a small claim could cost us our claims-free credit at renewal. The porch was maintenance from the start. Both times the money came from the house fund, which we try to keep above the deductible for exactly this reason. As long as that holds, the higher deductible matches how we actually use insurance: for the big, rare disaster, not the $2,000 surprise.
That's our situation, not a recommendation. A high deductible only works if you can actually pay it on your worst day, and policies differ in ways I'm still learning. Your own agent can run the numbers for your house.
Auto stays with GEICO for both cars. We priced bundles last year and none beat NYCM on the house alone, so I didn't run them again. The renewal went into the folder with Kevin's invoice, and I wrote "insurance, late Sept" on next year's kitchen calendar in green pencil, so I'll see it coming.